Licences and permitted operations
A licence applies to a specific operator and its operations, not to the software. Permits for the bank and the provider are checked in the country of deployment.
A platform for pilot deployment under the bank’s brand: exchange, wallets, KYC and AML. The range of operations, including P2P, OTC and payments, depends on jurisdiction and permits.
Digital assets are leaving the gray zone
Kazakhstan. From 1 May 2026, exchange services are licensed by the National Bank, and AIFC platforms processed $10.5B in transactions over the year, but up to 95% of turnover is still outside the legal perimeter — these are the clients banks will compete for. Uzbekistan. Crypto asset turnover doubled to $2B with two licensed exchanges, and a stablecoin payments sandbox is open to banks — operations are possible only through licensed providers and within the regime.
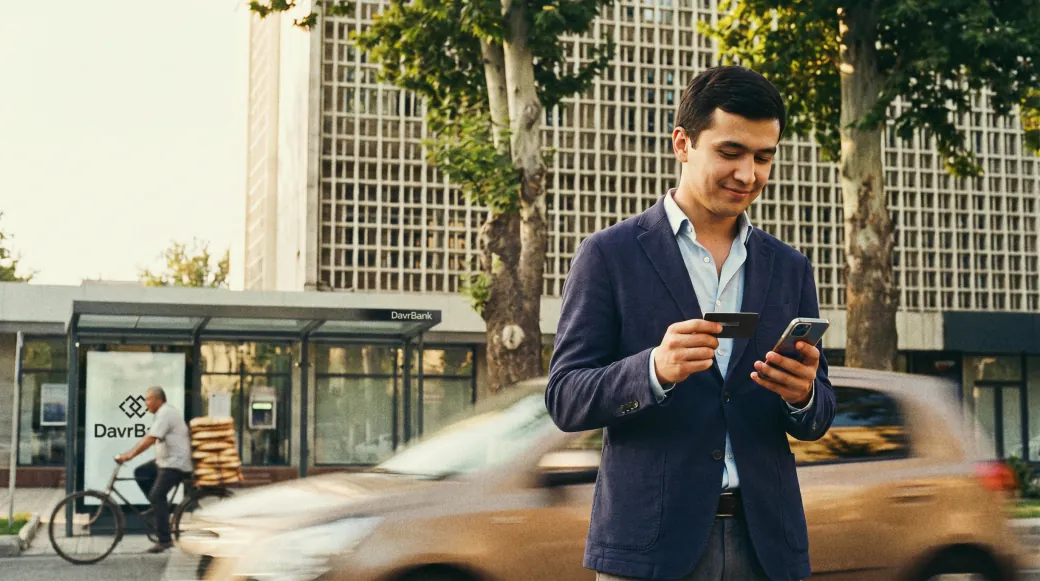
Digital assets in the bank’s app, under its brand, with KYC and AML
A pilot environment built on the technology of a licensed Kazakh exchange. Bank account integration, asset custody and permitted operations are defined during Discovery.
A licence applies to a specific operator and its operations, not to the software. Permits for the bank and the provider are checked in the country of deployment.
A pilot lets you test exchange and settlement scenarios. Having crypto payment infrastructure does not by itself confirm demand from the bank’s clients.
KYC, limits, screening of addresses, transactions and sanctions lists; a log and escalation of suspicious transactions to compliance.
Buying and selling with rates, fees and limits in the bank’s interface. Currency and settlement depend on the agreed model.
Listings, escrow, disputes, arbitration and ratings, where P2P is permitted in the chosen jurisdiction.
Requests for large deals, rate and settlement agreement, manager support and compliance documents.
Crypto asset conversion with settlement to the merchant in the national currency, subject to the required permits.
Order book, limit and market orders, matching on the exchange engine.
Bank KYC, verification levels and limits; document and liveness checks, event-driven re-verification.
Screening of addresses, transactions and sanctions lists, counterparty assessment, reporting for compliance and the regulator.
Wallets, hot and cold storage, signatures, withdrawal limits, accounting and reconciliation; custody responsibility is agreed separately.
Roadmap: issuance, accounting, circulation and redemption of digital financial assets. The legal regime and the underlying assets are reviewed separately.
Choice of operations, assets, format, provider, licences, limits and compliance requirements.
Testing of agreed operations with a limited group; KYC and AML are part of the pilot.
Enabling approved operations in the bank’s app and regulatory reporting.
New assets, custody and tokenization are separate stages, after readiness and permits are confirmed.
New operations, AML and regulatory reporting, SLA-based support. Delivery
Interface and integrations under the bank’s brand; data hosting and storage are agreed separately. Price and timeline are set in the contract.
Trades, order book and custody stay with the licensed provider; the bank connects via API without its own exchange engine.
AML, reporting and new assets: by subscription or handled by the bank’s team.
We build the digital assets team and processes, launch, and hand over to the bank once agreed targets are met. How it works
“Crypto in a bank is not about the bitcoin price, it is about the framework: verification, AML and clear rules for each country. What matters for a bank is launching exchange and payments under its own brand rather than losing clients to third-party platforms.”
 Oleg KachalinCo-founder, CEO in Uzbekistan Blog “Usataya Baza”LinkedIn
It depends on the country, operations, provider and licences. Using a licensed exchange’s technology does not replace the permits of the bank and the operator; the model is verified before the pilot.
The required permits depend on the operations and the bank’s role. The exchange’s licence does not extend to the bank; responsibilities are agreed with compliance during Discovery.
Screening of addresses, transactions and sanctions lists; risk scoring. Suspicious operations are escalated to compliance and logged.
The rate, fee, currency and settlement terms are shown in the app; opening a wallet goes through the required checks.
This scenario is scoped separately: conversion and settlement to the merchant in the national currency. Availability depends on the country, provider and permits.
After Discovery and the permit review comes a pilot, then launch. The timeline depends on operations, integrations and approvals and is set in the contract.
Your request goes to our business development team: we will get in touch, work out what needs to go live at your bank and propose a solution.
Thank you, your request has been sent
A business development manager will contact you using the details you provided.