Standard applications, automatically
Checks, scoring, documents and disbursement are combined in one process. The conditions for automatic processing are set by the bank’s credit policy.
Applications, checks, decisions and disbursement in a single process. Standard applications are automated according to the bank’s rules; exceptions go to an underwriter. Four products: consumer loan, card, installments and SME.
Online lending under new rules
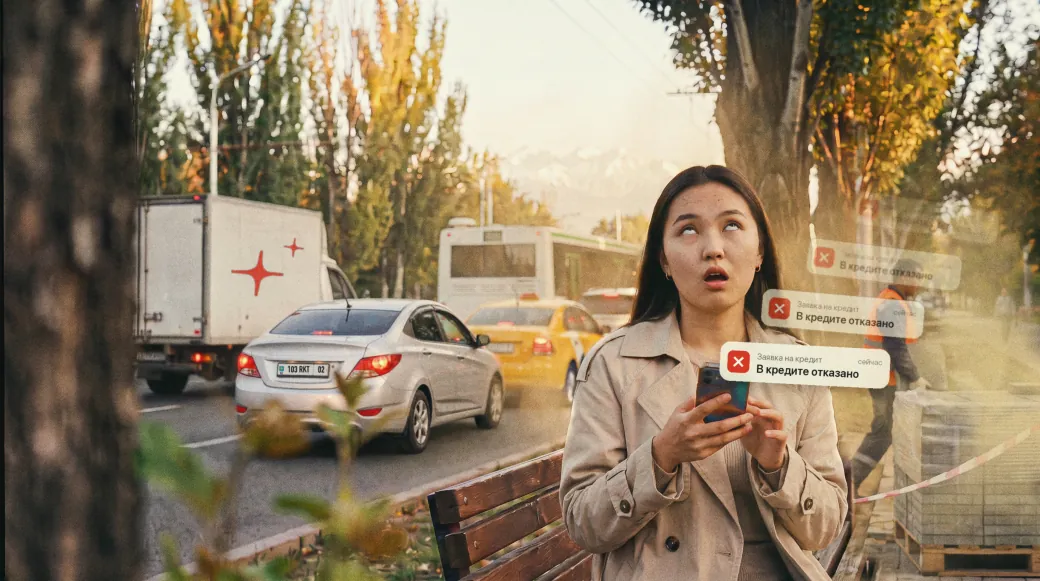
Kazakhstan. The regulator has narrowed the funnel: a cooling-off period, a questionnaire and biometrics before an online loan, one loan per hour, and banks approve only a third of unsecured applications — growth can come only from pipeline quality, not volume. Uzbekistan. The central bank has capped microloans with debt burden limits, and retail lending fell over the half-year, so banks are shifting their pipelines to secured products and business loans.
Standard applications are processed according to the bank’s rules, exceptions go to the underwriter
Ready Bank connects application channels, credit bureaus, biometrics, antifraud and the core banking system. The bank’s rules and models drive decisions; disbursement and accounting run in the core banking system.
Checks, scoring, documents and disbursement are combined in one process. The conditions for automatic processing are set by the bank’s credit policy.
Rules, model versions and check results are recorded for decision reviews. Exceptions go to the underwriter.
Identity and transaction checks are built into the application; the set and order of checks are agreed for the jurisdiction and product.
Mobile banking, website, branches and partner outlets. A single application form pre-filled from available data.

Credit bureau and government database queries, document verification, biometrics and antifraud within the application flow. Antifraud
Rule editor, the bank’s own models and ML scoring; rule versioning and backtesting on historical applications.
Automated decision and limit based on rules; exceptions go to an underwriter. Four-eyes principle and decision log.
Contract, payment schedule and offer generated from templates; e-signing in the app or at a branch.
Disbursement to an account or card, accounting in the core banking system, payment schedule, early repayment and handover of overdue loans to collections.
Configure consumer loans, credit cards, installment plans and SME loans: parameters, rates, terms and rules.
Funnel, decision time, automated decision rate, reports for risk and the regulator.
Integration with the core banking system, processing, credit bureaus, government databases and biometrics; in Uzbekistan, the Ready Bank service bus can be used. Compatibility is verified before implementation.
Audit of channels, checks and manual steps; choice of product and pilot KPIs.
Configuring the product, rules, models and integrations; enabling biometrics and antifraud.
Pilot on a share of applications: decisions, processing time and auto-decision rate compared with the current process.
Connecting products and channels; configuring exceptions and funnel reports.
Face, document and transaction checks; logging and reporting to agreed requirements.
The pipeline runs in the bank’s infrastructure; rules and models stay with the bank. Price and timeline are set in the contract.
Infrastructure, deployment and 24/7 monitoring by Rocket Tech; data storage terms are agreed with the bank.
New products, rules, models and retraining, by subscription or by the bank’s own team.
Building the lending team and processes, launching and handing over to the bank once agreed targets are met. How it works
“A pipeline is not a scoring model but the entire application journey, from the form to money in the account. Standard applications follow the bank’s rules, and underwriters spend their time on complex cases rather than routine.”
 Oleg SolabayevCTO, Head of Ready Bank products


The integration method is determined by an audit of the core banking system and master systems: direct or via an integration bus. Disbursement and accounting remain in the core banking system.
The bank’s rules and models; ML scoring is built on the bank’s historical data. The quality and explainability of the selected models are verified during implementation.
Biometric verification is built into the process in line with country and product rules. Specific requirements and services are agreed during implementation.
Yes. Start with one product, such as a consumer loan or a credit card; the rest are connected after the pilot.
Rules, model versions and a decision log; exceptions go to an underwriter, with “four-eyes” approval.
Audit, setup and pilot, then scaling. The timeline depends on products and integrations and is fixed in the contract.
Loans and instalments in the region’s banking apps
Your request goes to our business development team: we will get in touch, work out what needs to go live at your bank and propose a solution.
Thank you, your request has been sent
A business development manager will contact you using the details you provided.